S&P 500 Rally Hides Wider Stock Market Weakness as AI Giants Dominate Gains
NEW YORK, United States, 12 October 2026, ZEX PR WIRE — The S&P 500 has continued climbing toward record levels in 2026, but a closer look at individual stocks reveals a less uniform market recovery. More than 200 companies in the benchmark have recorded losses this year, even as strong performance from a relatively small group of artificial intelligence and semiconductor stocks has lifted the broader index.
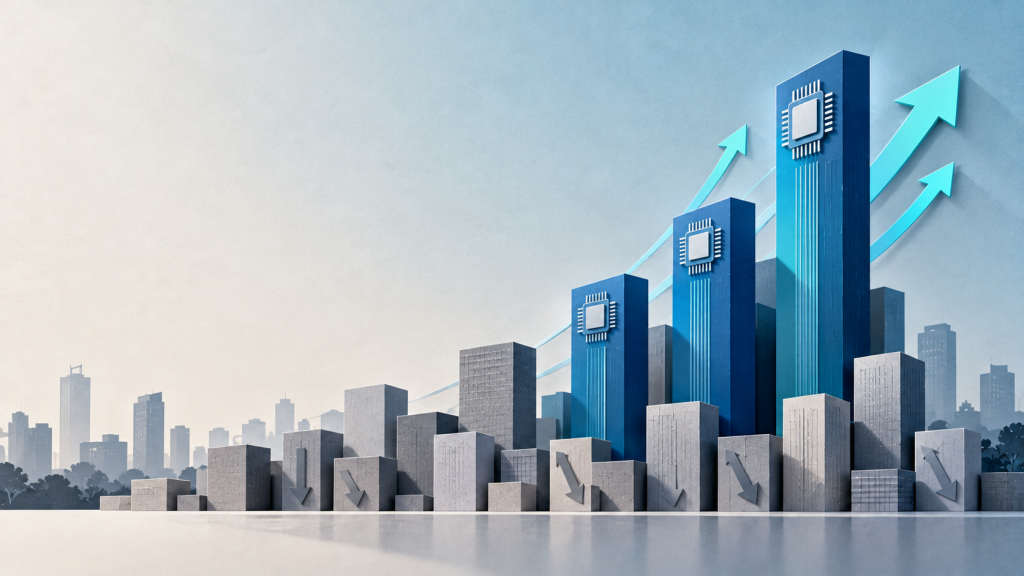
A Reuters analysis published on October 12 found that the S&P 500 had gained approximately 14% in 2026, while the median stock in the index had risen by only around 4%. The difference highlights how heavily the market’s performance has depended on a limited number of major technology companies.
For investors, the divergence raises an important question: does the index reflect broad corporate strength, or is its performance increasingly reliant on a handful of high growth businesses?
AI Stocks Are Driving Index Performance
Semiconductor companies have been among the strongest performers during the AI investment boom. Businesses supplying memory chips and advanced computing infrastructure have benefited from expectations of sustained spending on data centers and AI applications.
These gains have helped support major US indices because the largest companies carry significant weight in market capitalization weighted benchmarks. When a small group of high value stocks rises sharply, it can lift an index even when many of its constituents are declining.
The concentration creates a potential weakness. If leading technology stocks experience earnings disappointments, valuation pressure or a slowdown in AI spending, the impact on the broader benchmark could be substantial.
This does not necessarily mean the rally is unsustainable. It does mean investors need to distinguish between index performance and the experience of the average company.
Why Market Breadth Matters
Market breadth measures how widely gains or losses are distributed among stocks. A rally supported by companies across multiple sectors can indicate stronger participation, while a narrow advance may leave the market more exposed to setbacks in its leading constituents.
The Reuters analysis found that fewer than half of current S&P 500 companies were trading above their 200 day moving averages, a technical indicator commonly used to assess longer term price trends.
That measure suggests participation has remained uneven despite the benchmark’s overall advance. However, technical indicators do not independently predict when a market will reverse, and sector differences can persist for extended periods.
Investors may therefore look beyond headline index returns to compare sector performance, earnings growth and the number of stocks participating in the advance.
Higher Interest Rates Add Another Risk
The Federal Reserve’s September rate increase and expectations of further tightening have added pressure to parts of the market that are more sensitive to borrowing costs.
Higher interest rates can reduce the present value of future earnings, particularly for companies whose valuations depend on profits expected far into the future. They can also increase financing costs for businesses and consumers.
This environment creates different challenges across sectors. Technology companies with strong cash generation may remain relatively resilient, while businesses exposed to consumer spending, property or expensive financing could face greater pressure.
The combination of concentrated market gains and higher borrowing costs makes upcoming earnings reports especially important. Investors will need to assess whether profit growth is broadening beyond the companies that have led the rally.
What Investors Should Watch Next
The third quarter earnings season could provide a clearer picture of whether corporate performance is becoming more widespread. Revenue growth, profit margins and forward guidance will help determine whether companies outside the AI trade can contribute more meaningfully to market gains.
A broader advance would suggest that improving earnings are supporting a wider range of businesses. Continued concentration, by contrast, would leave the index more dependent on a small number of major stocks.
For investors, the key lesson is that a rising benchmark does not guarantee that the wider market is equally strong. Examining market breadth alongside earnings and valuations can provide a more complete view of the risks beneath the headline performance.