European Stocks Hold Near Record Levels as Investors Assess Earnings and AI Sector Risks
FRANKFURT, Germany, November 13, 2026, ZEX PR WIRE, European equity markets remained close to record territory after the STOXX 600 advanced modestly on Thursday, supported by corporate earnings and continued investor interest in sectors outside the artificial intelligence trade. The latest performance highlighted the region’s relative resilience as global investors reassessed valuations and risks in technology-related companies.
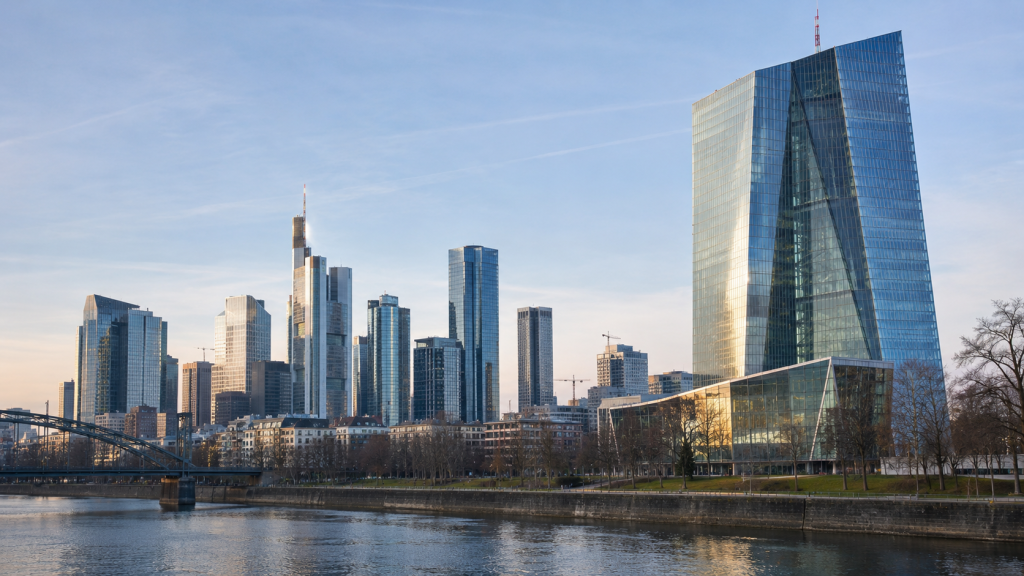
The pan-European STOXX 600 closed 0.14% higher at 664.01 points after reaching an intraday record of 666.58 points. Germany’s DAX also advanced 0.4%, setting a new record during the session. The figures reflected Thursday’s market performance, rather than a confirmed Friday closing result.
Corporate Results Support European Equities
Corporate earnings have remained an important source of support for European shares. Several companies have reported results that helped investors look beyond concerns about inflation, energy costs and potential interest rate increases.
Siemens gained 1.7% after the industrial technology company raised its medium-term growth outlook. The company’s updated expectations added to a broader positive response to earnings from European industrial businesses.
Adecco Group recorded a particularly strong move, with its shares rising 14.7% after the staffing and recruitment company reported better-than-expected third-quarter operating income. Its management also pointed to improving conditions for permanent recruitment.
These developments suggest that investors are continuing to differentiate between companies based on earnings performance and business outlook rather than treating the European market as a single investment theme.
AI Sector Rotation Changes Market Leadership
Another factor supporting European equities has been the rotation away from some AI-linked companies. Investors have become more selective about businesses exposed to the technology investment cycle, particularly where expansion plans rely on substantial capital expenditure or debt financing.
European markets have comparatively less concentration in major AI infrastructure companies than some US and Asian equity benchmarks. This difference has helped the region attract attention from investors seeking exposure to other industries, including healthcare, consumer businesses and industrial companies.
The change in market leadership does not necessarily indicate a broad decline in demand for AI technology. Instead, it reflects a more cautious approach towards valuations, funding requirements and the potential returns from large infrastructure investments.
Energy Costs and Interest Rates Remain Key Risks
European businesses continue to face uncertainty from energy prices and monetary policy. Higher oil and gas costs can affect manufacturing expenses, transport operations and household purchasing power. These factors may influence consumer demand and corporate margins if elevated prices persist.
Interest rate expectations are another important consideration. If inflation remains difficult to control, the European Central Bank may have less flexibility to ease monetary conditions. Higher borrowing costs can affect investment decisions and company valuations, particularly for businesses with significant financing requirements.
Earnings Remain Central to the Market Outlook
The latest performance indicates that European equities continue to receive support from corporate results and sector diversification. However, investors will need to assess whether earnings growth can remain strong enough to offset inflationary pressure and geopolitical uncertainty.
The region’s ability to sustain its relative performance may depend on the durability of business profits, the direction of energy prices and the extent to which investors continue shifting capital between technology and traditional industries.